How to Lower Credit Card Processing Fees: 9 Ways That Work
Card fees are often a business's third-biggest expense after payroll and rent. These nine steps can cut them, and the last one can nearly erase them.
1. Know your effective rate
Divide your total monthly fees by your total card sales. You can't lower what you don't measure. See how to read a merchant statement.
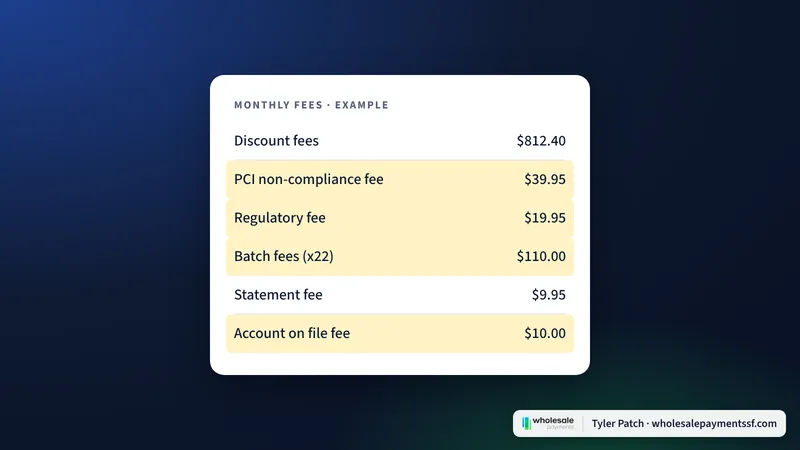
2. Remove junk fees
Look for PCI, regulatory, batch, statement and "account on file" fees. Many of them can be removed or avoided. Here's our list of nine hidden fees.
3. Get off tiered pricing
Tiered pricing lets processors push more sales into expensive "non-qualified" buckets. Interchange plus or a cash discount program is easier to check.
4. Stop leasing equipment
A terminal lease can run for years and cost far more than the terminal is worth. Ask about buying or other options.
5. Dip or tap, don't key in
Keyed-in cards cost more and carry more fraud risk. Use chip and tap whenever the customer is present.
6. Batch out daily
Closing your batch every day helps transactions qualify for the best rates and gets your money to you faster.
7. Fight chargebacks the right way
Chargebacks come with fees and lost sales. Keep receipts and signatures, and respond fast. Read chargeback help.
8. Review your statement every year
Rates creep up quietly. Compare this month's effective rate to one from a year ago.
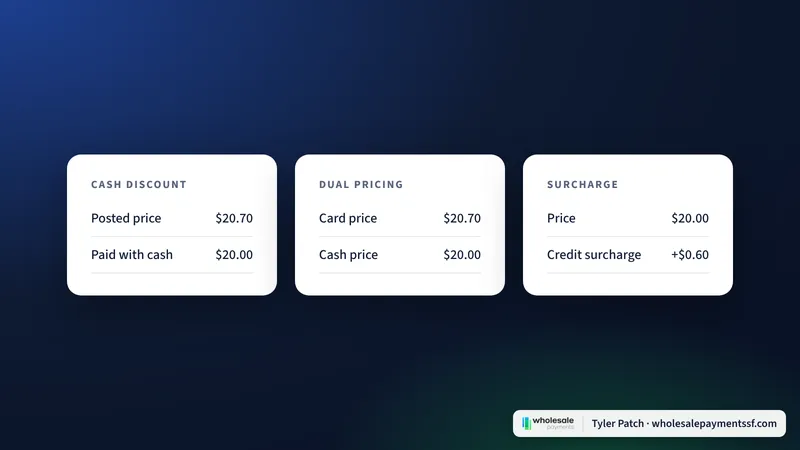
9. Switch to a cash discount program
This is the big one. With cash discount or dual pricing, card customers cover the processing cost and cash customers get a discount. Processing fees can drop to near zero. Federal law protects discounts for cash, and it works on debit cards too, unlike surcharging. Compare the options in cash discount vs. surcharge vs. dual pricing.
See your number
Plug your monthly card sales into the card fee calculator to see what card fees cost you each year.
Frequently asked questions
What is the fastest way to lower credit card processing fees?
A compliant cash discount or dual pricing program, where card customers cover the processing cost. It can drop processing fees to near zero.
Can I negotiate my credit card processing rates?
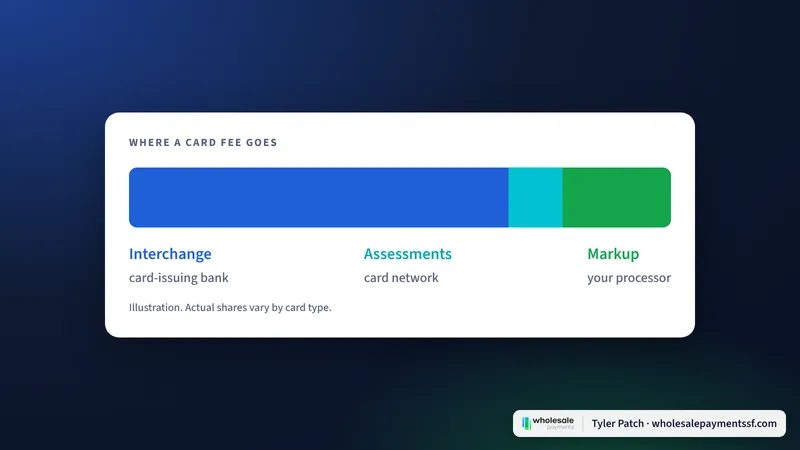
Often, yes, especially the processor markup and monthly fees. Interchange is set by the card networks and can't be negotiated.
How often should I review my merchant statement?
At least once a year, and any time your fees seem higher than usual. Compare your effective rate over time.
Questions about your own setup? Text Tyler.
General information only, not legal, tax or financial advice. Card network rules and state laws change, so confirm current rules before you change your pricing.